For workforce companies where distribution is the difference.

Strategic advisory, go-to-market execution, and capital for HR tech, payroll, and benefits companies.

We work on every side of the market

A workforce product travels from the people who build it, through the channels that carry it, to the leaders who buy it. Tharseo is active at each step.

Builders

Founders and operators building workforce products.

We build, advise, and back them.
StashWorks Boomerang Rising Team Atonom OneRange Payroll Pulse One Haven Soar / Workplace AI

Distribution channels

The payroll and HCM platforms in the marketplace. Their partner teams shape the shortlist.

We work alongside them.
ADP Workday UKG Dayforce Paychex Paycom Paylocity Paycor isolved Rippling Gusto

Buyers

Senior HR and People leaders who make the decision.

We advise them.
thesis. People Performance Institute
STRATEGIC ADVISORY GO-TO-MARKET EXECUTION CAPITAL

Three ways we work with a company

Strategic advisory

Strategy, positioning, and revenue design for leadership teams. We advise and your team executes.

Go-to-market execution

Fractional commercial leadership that builds the motion and runs it alongside your team.

Capital

Selective investments in companies where our experience and relationships improve the odds.

From the Journal

View All Essays
Rows of identical person icons sorted into groups. A gold line runs from one person through a contact in another group to a buyer inside a highlighted company
Whitepaper
The Trust Economy
13 min readRead →
Two halves of an unfinished concrete bridge that stop short of each other
Distribution
Why HR Tech Distribution Is Broken
8 min readRead →
A player holding a fanned hand of playing cards close
Market Intelligence
What HCM Platforms Aren't Telling Their Clients
6 min readRead →

Tell us the company, the stage, and the problem.

The first call runs 30 to 45 minutes. By the end, we will tell you whether Tharseo can help.

What We Do

Strategic advisory, go-to-market execution, and capital for workforce companies.

Three ways to work with Tharseo, and how an engagement runs.

01

Strategic advisory

For leadership teams
setting the commercial plan

Strategy and thinking partnership on where to play, how to position, and what the revenue engine should look like. We advise and your team executes.

  • Go-to-market strategy and positioning
  • Revenue architecture and sales design
  • HCM and payroll platform strategy
  • Ecosystem mapping and sequencing
02

Go-to-market execution

For companies that need
the motion built and run

Fractional commercial leadership that builds the motion and runs it alongside your team. The remit covers marketing, revenue operations, partnerships, pricing, and customer success as well as sales.

  • Interim or fractional CRO leadership
  • Pipeline discipline, cadence, and forecasting
  • Team design, coaching, and key hiring
  • Buyer, platform, and channel introductions
03

Capital

For companies
we can also help

We make selective investments where our experience and access improve the odds. Portfolio companies get the same support as advisory and execution clients.

  • Early and growth-stage equity
  • Hands-on market diligence
  • Post-investment go-to-market support
  • Long-term alignment beyond the transaction

How an engagement runs

Senior operators in sales, marketing, revenue operations, and partnerships join on a fractional basis when a problem calls for one.

Economics are advisory fees, equity, or success-based terms, depending on the engagement.

Introductory Call30 to 45 minutes on the company, the stage, and the problem. We tell you whether we can help.
DiagnosticA focused review of the commercial motion and the market opportunity.
Engagement DesignScope, timeline, and economics set around the problem.
Operating RhythmA weekly cadence and direct access for the length of the engagement.

Have a growth or distribution problem to work through?

Portfolio

Companies we help build, back, and advise.

Ten companies across HR technology, payroll, benefits, training, and workforce AI. Each card shows our role.

StashWorks
Financial Wellness Benefit
A workplace benefit that lets employees save, invest, and earn cash rewards from their paycheck at no cost to them.
Strategic Advisor
thesis.
Institute for the Future of Work
An institute that publishes numbered positions on how work is changing, each one sourced, challenged, and revised on the record.
Venture · Active Operator
Boomerang
Alumni Hiring · HR Tech
An alumni labor cloud that turns former employees and silver medalists into a hiring channel.
Equity · Strategic Advisor
Rising Team
Leadership Development
An AI-powered leadership development platform that helps managers improve in the flow of work.
Equity · Strategic Advisor
Atonom
AI Employees
AI employees that build pipeline, resolve support tickets, and handle recruiting across sales, support, and HR.
Strategic Advisor
OneRange
AI Workforce Training
An AI training platform that assesses where each employee stands, trains the skills the role needs on the company's own material, and shows proof of skill.
Equity · Strategic Advisor
Payroll Pulse
HR Tech Marketplace
A vendor selection marketplace that helps organizations evaluate, select, and negotiate HR and payroll technology.
Venture · Active Operator
One Haven
Family Digital Safety
A privacy-first family digital safety platform delivered through employers as a benefit.
Equity · Strategic Advisor
People Performance Institute
HR Consulting
IO psychology for mid-sized businesses.
Venture · Active Operator
Soar / Workplace AI
Workplace Intelligence
An AI studio and workplace intelligence company working across people, data, and systems.
Equity · Strategic Advisor

How we select

We get involved when the team is strong, the buyer pain is clear, and our experience or relationships can change the outcome.

Team
Operators who know the market they are entering.
Market
Buyer pain that is clear, with timing on its side.
Model
A business that works without the next financing round.
Fit
A place where our access and experience move the result.
Journal

Notes from inside the market.

Essays and research on distribution, platforms, and buying in workforce technology.

Two halves of an unfinished concrete bridge that stop short of each other
Distribution
Why HR Tech Distribution Is Broken
Why strong products stall in HR tech, what it costs founders, and what to do about it.
8 min readRead →
A player holding a fanned hand of playing cards close
Market Intelligence
What HCM Platforms Aren't Telling Their Clients
How platform partnerships and roadmaps shape what HR buyers see.
6 min readRead →
A full boardroom meeting around a long conference table
Operator Perspective
The Operator's Case for Benefits as a Distribution Channel
Why the employer channel is becoming a distribution path for consumer-grade products.
7 min readRead →

Have a market or operator question worth an essay?

Suggest a Topic
Back to Journal
Whitepaper

The Trust Economy

Anyone can look like a great company now. Buyers know it, and it is changing how they decide.
George RiveraAugust 12, 202613 min read

Who this is for: founders and revenue leaders selling into HR, payroll, and benefits.

In brief
  • Polish no longer proves anything. Websites, demos, case studies, and testimonials now cost almost nothing to produce, so they no longer help a buyer tell a strong vendor from a weak one.
  • Buyers are deciding earlier and closer to home. In 2025 the winning vendor was on the buyer's day-one shortlist 95% of the time, up from 85%, while cold outreach lands less often every year.
  • Credibility now comes three ways: someone the buyer already trusts vouches for you, the buyer can check your claims without taking your word for it, or you pay if you turn out to be wrong.

A small company can now look like a large one in a matter of days.

The website, the product video, the deck, the case studies, and the page of customer quotes used to take a team, a budget, and months of work. They now take a few days and almost no money. Some of what gets produced is true, and the buyer has no way to tell which part.

Buyers know this. They have less reason to give any of it credit.

The cost of appearing credible is approaching zero. The cost of being credible has not moved. That is the change this paper is about. Presentation used to be evidence. A company that looked established usually was, because looking established was expensive. That link is broken, and buyers are adjusting faster than the companies selling to them.

They decide earlier. They lean harder on the vendors and people they already know. When the stakes are real, they want a person who can be held to what was said.

I wrote in April that distribution in HR tech is a trust problem first and a sales problem second. HR tech has been bought through peers, platforms, and advisors for as long as I have worked in it. The research below shows large B2B purchases across technology, services, and manufacturing being made the same way.

I want to say one thing about cause before the evidence. Many people want to pin this on AI. I do not think it needs to be pinned on any one thing. Trust in institutions has been falling for years, budgets are tight, and every buyer is buried in content. AI adds to all of that by putting a polished first impression within anyone's reach. What matters to an operator is the behavior, and the behavior has changed.

Getting a meeting has never been harder

Ask any seller what changed in the last two years and you will hear the same answer: nobody picks up.

The data backs them up. In The Bridge Group's 2025 survey of sales development teams, 60% of reps hit quota, the lowest share in the study's history. Companies have cut the monthly meeting quotas for those reps by 40% since 2018. Belkins tracked 7.5 million cold emails sent in 2025 and got a reply to fewer than one in two hundred, with the rate falling from 0.50% in the first half of the year to 0.40% in the second. Its calling data from the same year works out to roughly one booked meeting for every 370 dials. And in Gartner's 2024 buyer survey, 73% of B2B buyers said they actively avoid suppliers who send irrelevant outreach.

Some of that is volume. Inboxes are fuller, spam filters are stricter, and plenty of outreach is badly aimed. The rest is the trust problem showing up at the front door. A stranger's email looks like every other stranger's email, so buyers have stopped answering strangers. The meetings still happen. They come through someone the buyer already trusts.

We lost a deal at one of our portfolio companies that came down to exactly that. The competitor's original introduction came from someone at the buyer's private equity investor. From then on, nothing we could put in a deck was going to outweigh a recommendation from the firm that owns the company.

Looking good is cheap now

Economists described this problem more than fifty years ago.

In 1970, George Akerlof showed what happens when buyers cannot tell a good product from a bad one. They stop paying extra for good, and the honest sellers are the ones who lose. Three years later, Michael Spence explained what keeps a market like that working. The side that knows more sends a signal, and the signal means something only when it costs a weak candidate more to send than a strong one. His example was job applicants and education. The same logic applies to companies and their buyers.

Polish used to be that kind of signal. A serious website, a produced video, and a steady stream of content told a buyer that someone had invested real money.

First impressions of polish form fast. In one well-known study, people rated the visual appeal of web pages after seeing them for 50 milliseconds, and those ratings closely tracked the ones they gave after half a second.

That signal now costs almost nothing to send, and the imitation can beat the original. In a 2022 study, people could not reliably tell AI-generated faces from photographs of real people, and they rated the generated faces as 7.7% more trustworthy on average. In 2024 the FTC banned fake reviews and testimonials. The agency's commentary on the rule says AI tools let bad actors generate large numbers of realistic fake reviews quickly and cheaply.

A signal that costs nothing to send tells the buyer nothing.

That is where website polish, content volume, produced demos, and written testimonials are heading.

Buyers have noticed

In October 2025, Gartner surveyed 1,539 U.S. consumers. Of those, 68% said they frequently wonder whether the content they see is real, and 61% frequently question whether the information they use for everyday decisions is reliable. Half said they would rather give their business to brands that keep generative AI out of customer-facing content.

The mood is wider than marketing. Trust in news across 48 markets fell to 37% in 2026, the lowest the Reuters Institute has recorded since it began measuring in 2015. It was 42% in 2022 and held at 40% for the three years after. In the United States the figure is 25%.

Trust in news fell to 37% in 2026, the lowest since tracking began in 2015
Share who trust news most of the time, average across all markets surveyed
42%202240%202340%202440%202537%2026 42%202240%202340%202440%202537%2026
Source: Reuters Institute Digital News Report, 2022 to 2026.

Edelman found that 70% of people across 28 countries are hesitant or unwilling to trust someone whose values, sources of information, approach to problems, or background differ from their own. Pew found Americans split almost evenly on whether they can tell what is true in the news: 51% say it is difficult and 49% say it is easy.

None of those surveys is about buying software. I include them because the people who answer them are the same people who sit on buying committees, and I do not believe they set that skepticism aside at work.

What buyers do now

Skepticism matters when it changes what buyers do. Three behaviors show up clearly in the data.

Buyers settle on a vendor earlier and want sellers less
Earlier reading in green, latest in gold
Winner was on the day-one shortlist6sense, 2024 vs 2025 study85%95%Buyers who prefer no sales repGartner, 2024 vs 2025 survey61%67%Pre-contact favorite won the deal6sense, earlier years vs 202583%77%50%100% Winner was on the day-one shortlist6sense, 2024 vs 2025 study85%95%Buyers who prefer no sales repGartner, 2024 vs 2025 survey61%67%Pre-contact favorite won the deal6sense, earlier years vs 202583%77%50%100%
Sources: 6sense Buyer Experience Reports 2024 and 2025; Gartner B2B buyer surveys fielded 2024 and 2025.

They decide before you show up. 6sense surveyed nearly 4,000 B2B buyers in 2025, with a median purchase between $200,000 and $300,000. The winning vendor was on the buyer's shortlist on day one 95% of the time, up from 85% a year earlier. Buyers already had experience with 3.8 of the roughly five vendors they evaluated, up from 3.2. Before speaking to a single seller, 94% had ranked that shortlist, and their first choice went on to win 77% of the time.

Those numbers describe a sale that is mostly decided before the first call. The buyer arrives with a favorite, and the favorite wins about three times out of four. That share was 83% in earlier years, so sellers do change some minds. Most of the conversations that follow confirm a choice the buyer already made.

That does not make sellers irrelevant. In the same research, buyers first contacted a seller 61% of the way through their process, earlier than the 69% found in previous studies. They come to sellers sooner, and they come to check what they have already started to believe. The credibility has to be in place before that call.

They go with who they know. In the same study, 85% of buyers had prior experience with the vendor they chose, and three in four personally knew a seller at the vendors they evaluated. In a companion survey, about 70% said economic uncertainty pushed them toward more conservative choices, meaning known vendors and incumbents.

One field experiment shows what rising distrust does to behavior. The German newspaper Süddeutsche Zeitung showed a random group of its readers how hard it is to tell real images from AI-generated ones. Those readers came away trusting news less, including the newspaper that ran the test. In the days that followed they visited its site more often, and five months later more of them were still subscribers.

Less trust in news overall came with more engagement with a source those readers already rated highly. The authors read the result as trusted sources becoming more valuable as misinformation spreads. I expect the same in buying. When buyers cannot judge the unfamiliar, they keep buying, and they buy from the names they already trust.

They want someone on the hook. Gartner surveyed 645 B2B buyers in August and September 2025 and published two findings that look like a contradiction. In that survey, 67% said they prefer to buy without a sales rep, up from 61% a year earlier, and 69% said they prefer to validate AI-generated insights with a rep.

A third number from the same survey explains it. Asked where they are more likely to run into misleading information, 51% said generative AI and 49% said a sales rep. By that measure the rep and the chatbot are about equally likely to mislead.

Part of the reason is plain expertise. Buyers need product detail, technical answers, and help sorting out competing claims. My read is that accountability is the bigger part. A rep's answer comes with a name and a company attached, and the buyer can hold both to it. A seller's value now sits in standing behind what the buyer was told.

6sense saw the same pull from another direction. In its companion survey, 58% of buyers said they contacted sellers earlier than they otherwise would have, because they needed answers about the AI inside the products they were evaluating.

Four popular answers I do not buy

"Buyers will freeze." I understand why people believe this. Deals do stall. Forrester reports that 86% of B2B purchases stall at some point in the process. The research behind The JOLT Effect covered 2.5 million recorded sales calls and found that 40% to 60% of deals end in no decision.

That research began in March 2020, before generative AI reached buyers. The 6sense data from 2025 shows buying cycles about a month shorter globally and nearly unchanged in North America. What I see is caution. Buyers narrow the field early and choose the safe name. For a challenger that is worse than a freeze, because a frozen buyer can still be won.

"More content will fix it." Buyers in Gartner's 2025 survey already used seven information sources on average for a single purchase. Gartner also surveyed 1,464 B2B buyers and consumers about personalized marketing. It does sell: people who experienced it were 1.8 times more likely to pay a premium. They were also twice as likely to feel overwhelmed by the volume of information and 2.8 times as likely to feel time pressure to move forward. The 53% who had a negative experience with it were 3.2 times more likely to regret the purchase.

Committees make it worse. In Gartner's 2024 survey of B2B buyers, 74% of buying teams showed unhealthy conflict. Content tailored to individuals damaged group consensus, and content built for the whole buying group improved it. My read is that when every stakeholder arrives with a personal feed and a personal AI assistant, the group starts further apart.

More research does not rescue anyone either. In a study published in Nature, people who searched online to check a false news story became more likely to believe it. Their searches could land on low-quality sources that agreed with it.

"Just be authentic." This one is close, but it is too loose to act on. Across seven experiments, people who believed an emotional brand message was written by AI became less loyal and less likely to speak well of the company. The penalty shrank for factual messages, when AI only edited the message, and when people believed most marketing is written by AI.

That gives a workable rule. AI costs you little on a spec sheet or a comparison table. A thank-you, an apology, or a note from the founder should be written by a person.

"Show them proof." That works only when the proof is hard to fake. A case study is a document and a testimonial is a paragraph. Both cost almost nothing to produce now, and I expect buyers to discount them accordingly.

Three ways to be believed

The proof that still works is hard to fake. It reaches a buyer in one of three ways.

Someone vouches for you. A person the buyer already believes puts their own reputation behind yours. Edelman found that among people who trust an influencer, a majority would reconsider a company they distrust if that person vouched for it. In HR tech the influencer is a peer, a broker, a consultant, an investor, or a partner manager at the payroll platform. A buyer who cannot verify the vendor can still verify the person vouching, because they know that person and that person has a reputation to lose.

The buyer can check it. The claim can be tested without taking your word for it: a live test on the buyer's own data, a delivery record anyone can look up, a customer the buyer finds on their own instead of one you hand them.

You pay if you are wrong. A guarantee with money behind it, service credits, pricing tied to the outcome. This is the logic Spence described in 1973. A 2005 experiment on online merchants tested a money-back guarantee, branding, and a privacy statement as signals of a trustworthy seller. The results matched what signaling theory predicts.

Cheap to fake Hard to fake
Website and brand polish A peer who vouches for you
Testimonial quotes A customer the buyer finds on their own
Written case studies A delivery record the buyer can check
A produced demo A live test on the buyer's own data
Claims of scale Pricing tied to the outcome
Promises in the proposal A guarantee with money behind it

Each of the three can be gamed. A reference can be coached. A guarantee buried in exclusions is worth nothing. Outcome pricing invites arguments about how the outcome gets measured. The test is the same for all of them: would it hurt the seller if the claim turned out to be false?

Trust travels through people who have something to lose by being wrong.

This favors the names buyers already know

Everything above works in favor of companies that are already known.

If the shortlist is set on day one and filled with familiar names, the best product in a category can lose to the third-best product with better relationships. I have watched that happen in HR tech for twenty years, and I expect it to become more common in more markets.

I think that is bad for buyers, and it is worth being honest about why. Trust can protect companies that have not earned it. An incumbent can win with a worse product. A middleman can gain influence because it already has the buyer's ear, whatever its incentives. The deal we lost to the private equity introduction may have gone to the better product. Nobody in that room had a way to know. That is why a recommendation is not enough on its own, and why proof a buyer can check matters as much as the person who vouches.

It is also the opening for challengers.

Most challengers answer a trust problem with more marketing: more content, more outbound, more polish. That is money spent on the signals buyers now discount. The companies that break through will spend it on being known by the right few hundred people, and on proof that would hurt them if it were false.

What I would do

Here is where I would put the effort if the market did not know my company yet. The moves follow the three ways to be believed.

Get vouched for

  1. Get known before there is a deal. You cannot sell your way onto a list that was written before the buyer called anyone. Be present where your buyers talk to each other: the peer communities, the platform partner teams, and the brokers and advisors they call first. Measure the team on how often you make the shortlist.
  2. Borrow trust until you have earned your own. That means a customer who will take a call, a partner the buyer already uses, or an advisor with their own name at stake. One person the buyer knows saying you are good can do more than your website will. Pair it with proof the buyer can check, because a recommendation can be wrong.

Make it easy to check

  1. Sell to the room. Build one story the whole committee can repeat to each other, with numbers the CFO, the IT lead, and the end user can each check. Retire the content built to tell each stakeholder something different.
  2. Make every claim easy to check. In Gartner's 2024 survey, 69% of buyers said the vendor's website and the vendor's sellers gave them inconsistent information. Fix that first. Then assume everything you publish will be fed to an AI and compared with your competitors, because 94% of buyers in the 6sense study already use these tools during a purchase.
  3. Be honest about where the machine is. Use AI for the spec sheet, the summary, and the comparison table. Write the hard emails yourself, and sign your name.

Put something on the line

  1. Put money behind your claims. Guarantee the outcome on terms a buyer can actually enforce, price against it, or run a pilot on the buyer's own data with the pass mark agreed up front. A buyer has little reason to bet on a product its own maker will not bet on.
  2. Change what your sellers are for. A rep who recites features is repeating what the buyer's AI assistant already said. A rep who can tell a buyer what will go wrong in month three, and what the company will do about it, is doing a job software cannot do.

None of this is free. A guarantee puts real money at risk. A pilot ties up your best people for weeks. Outcome-based pricing pushes revenue out and makes the forecast harder to call. Showing up in the communities your buyers trust takes years to pay back, and it never appears in a quarterly pipeline report. A company with twelve months of runway cannot do all seven at once.

If I had to sequence it, early-stage companies should start with borrowed trust and pilots, because both cost time more than cash. Guarantees and outcome pricing come once you know your numbers well enough to bet on them. Community presence starts on day one, because it is the slowest to pay back.

Where I could be wrong

There are three things I cannot prove yet.

I cannot tell you how much of this is AI and how much is years of falling trust and tight budgets. I have stopped needing to. The buying behavior is the same either way.

Nobody has measured what proof is worth. I believe a challenger with a guarantee and three customers who pick up the phone can get onto a shortlist it was not on. I have not found data that shows it, and that is the research I would most like to see.

AI may also end up fixing part of the problem. Buyers already use it to compare vendors and check claims. If checking gets cheap enough, the best product wins more often. I hope that happens, and I am planning as if it will not.

The question to ask

Most go-to-market playbooks are built to win attention. The harder job now is being believed.

The question I would put to any company, including my own, is what it has that would be expensive to fake.

If the answer is a delivery record, customers who vouch for you, and claims you are willing to bet on, the next few years will be good to you. If the answer is a great website, there is work to do.
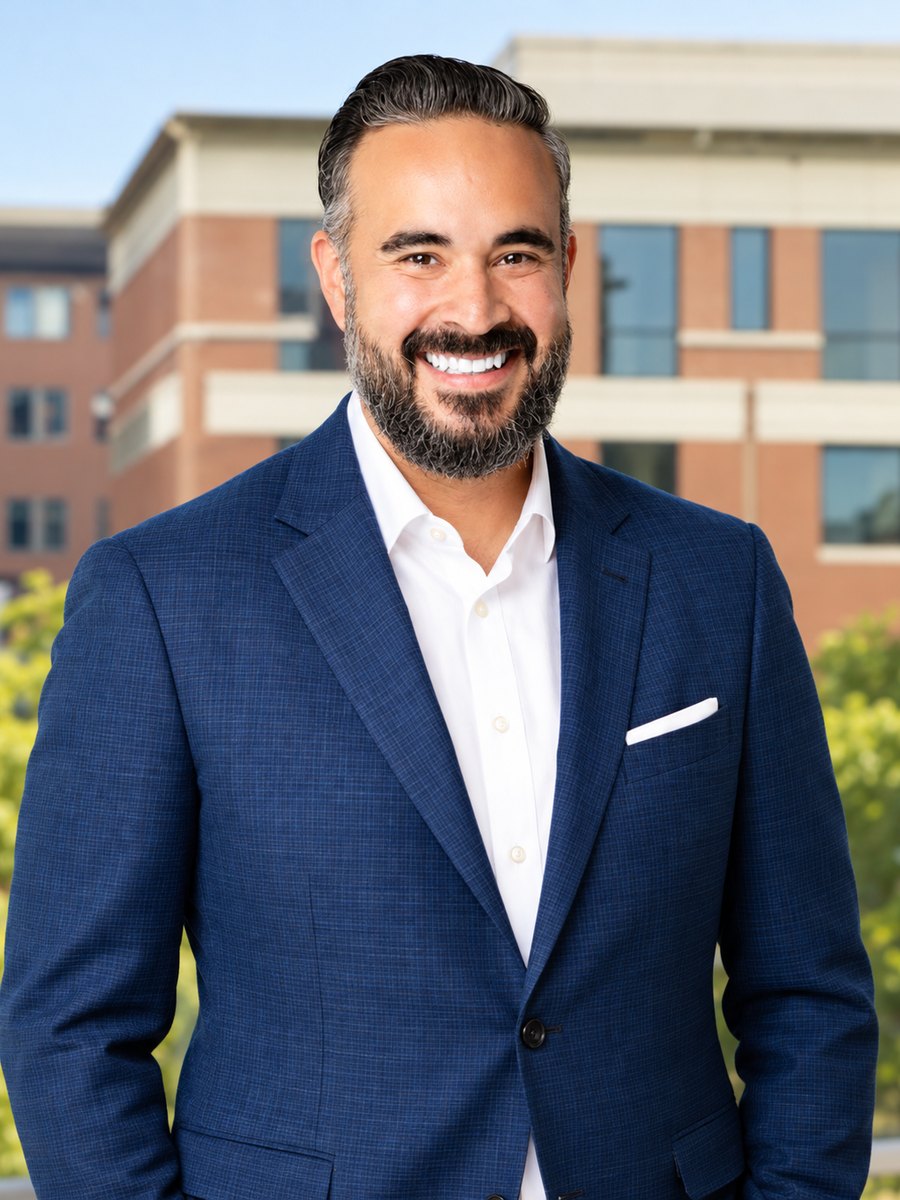
§George Rivera · Founder, Tharseo Group
Sources
  1. Akerlof, George. The Market for "Lemons": Quality Uncertainty and the Market Mechanism. Quarterly Journal of Economics, 1970.
  2. Spence, Michael. Job Market Signaling. Quarterly Journal of Economics, 1973.
  3. Lindgaard, Fernandes, Dudek, and Brown. Attention web designers: You have 50 milliseconds to make a good first impression! Behaviour & Information Technology, 2006.
  4. Nightingale and Farid. AI-synthesized faces are indistinguishable from real faces and more trustworthy. PNAS, 2022.
  5. Federal Trade Commission. Final rule banning fake reviews and testimonials. August 14, 2024. Rule commentary on AI as quoted in Sidley's summary of the rule.
  6. The Bridge Group. SDR Models, Motions & Metrics: 2025 Research Report, cited by the publisher as Sales Development Models, Metrics & Compensation, 10th edition. February 2025.
  7. Belkins. B2B cold email response rates, 7.5 million emails sent in 2025, and B2B cold calling benchmarks, 175,000 dials in 2025. June 2026.
  8. Gartner. Survey of 1,539 U.S. consumers, fielded October 2025. Released March 16, 2026.
  9. Reuters Institute. Digital News Report 2026. June 2026. 2022 figure from the Digital News Report 2022.
  10. Edelman. 2026 Edelman Trust Barometer. 33,938 respondents in 28 countries, fielded October to November 2025.
  11. Pew Research Center. Survey of 5,153 U.S. adults, fielded August 2025. Published October 29, 2025.
  12. 6sense. 2025 B2B Buyer Experience Report. Nearly 4,000 B2B buyers, plus a companion survey of 766. North America cycle figures and first-contact timing from this summary of the study.
  13. Campante, Durante, Hagemeister, and Sen. GenAI Misinformation, Trust, and News Consumption: Evidence from a Field Experiment. NBER Working Paper 34100, 2025.
  14. Gartner. B2B buyer survey fielded August to September 2025, about 645 buyers. Releases of March 9, 2026 and May 20, 2026.
  15. Gartner. B2B buyer survey fielded August to September 2024, 632 buyers. Releases of May 7, 2025 and June 25, 2025.
  16. Gartner. Survey of 1,464 B2B buyers and consumers, fielded November to December 2024. Released June 3, 2025.
  17. Forrester. The State of Business Buying, 2024. December 4, 2024.
  18. Dixon, Matthew, and Ted McKenna. The JOLT Effect, 2022. Figures as described in this interview with Dixon. Start date from Notion Capital's account of a Dixon presentation.
  19. Aslett, Sanderson, Godel, Persily, Nagler, and Tucker. Online searches to evaluate misinformation can increase its perceived veracity. Nature, 2024.
  20. Kirk and Givi. The AI-authorship effect. Journal of Business Research, 2025.
  21. Lee, Ang, and Dubelaar. Lemons on the Web: A signalling approach to the problem of trust in Internet commerce. Journal of Economic Psychology, 2005.
More from the Journal
Distribution
Why HR Tech Distribution Is Broken
8 min readRead →
Market Intelligence
What HCM Platforms Aren't Telling Their Clients
6 min readRead →
Back to Journal
Distribution

Why HR Tech Distribution Is Broken

Good HR technology products lose all the time. The reason is usually distribution.
George RiveraApril 20268 min read

In twenty years inside HR technology and workforce businesses, I have seen the same thing happen over and over again.

A company builds a better product than the incumbent. The demo is strong, the use case holds up, and the buyer pain is obvious. The team assumes the market will eventually figure it out.

Then adoption moves slowly. Sales cycles drag, partnership conversations stall, and the company burns months trying to create demand that should already exist.

Most of the time, the problem is distribution.

HR tech is a hard category to sell into. The buyer is rarely the daily user. The decision-maker is influenced by peers, brokers, HCM partners, consultants, benefits advisors, finance, procurement, and whatever system of record already sits at the center of the company.

By the time a founder gets a meeting, the buyer may already have a shortlist shaped by conversations the founder was never part of.

That is the part most companies miss.

The three gatekeepers nobody talks about

When founders say "distribution," they usually mean sales motion.

Outbound, pipeline, demo conversion, forecast discipline. Those matter, and they are only part of the job.

In HR tech, the harder part sits with three groups that shape who gets considered.

  • The HCM and payroll platforms. Workday, ADP, UKG, Rippling, Gusto, Paycom, and others influence the market far beyond their own products. Their partner teams, marketplaces, account executives, and product roadmaps all affect which vendors get oxygen.
  • The practitioner communities. Senior HR and People leaders talk constantly. They ask each other what is working, who to avoid, which vendor overpromised, and which founder understands the problem. If a company is not part of those conversations, it may never make the shortlist.
  • The consulting, broker, and advisor orbit. Benefits brokers, HR consultants, advisory firms, and implementation partners often sit between the vendor and the buyer. They recommend, filter, negotiate, and influence who gets in the room.
In HR tech, distribution is a trust problem first and a sales problem second.

What this costs

A credible HR tech company can spend nine to fourteen months moving from first meeting to signed contract. Sometimes longer.

A company with access, category credibility, and a partner path can compress that cycle. The product is the same. The company reaches the right conversation faster, with more trust already in the room.

That difference compounds.

A few months saved on each serious opportunity can change a fundraise, a hiring plan, or whether the company has enough time to reach the next stage.

I have watched strong products lose to weaker competitors because the weaker competitor had better distribution. It happens constantly.

Distribution cannot be faked

This is what makes HR tech different from many other SaaS categories.

You cannot buy this kind of distribution with ads, hire it overnight, or create it by being loud on LinkedIn. Trust takes longer than a quarter to build.

The relationships that matter are built through repeated exposure, useful work, good judgment, and showing up in the market long before you need something.

That is frustrating for founders because it means distribution has a time component. It is also the opportunity. If you reach the right relationships before your competitors do, the advantage holds.

What founders should do

There are three moves worth taking seriously.

First, build distribution the way you build product. If outbound is not working, more volume may not fix it. The problem may be credibility, access, or sequencing.

Second, find operators who already understand the market. Advisors, fractional leaders, investors, and partners are valuable when they have context. Ask who they know and where they have helped. Have them explain the buyer dynamics before you let them near the strategy.

Third, build the HCM and ecosystem strategy deliberately. A partnership works when the platform, the account team, the buyer, and the vendor each have a reason to care. A marketplace listing alone gives none of them one.

The companies that figure this out early have an advantage that is hard to catch. The ones that do not often spend years building a product the market should want, but never learns how to buy.

§George Rivera · Founder, Tharseo Group

Building in HR tech or payroll?

Every Tharseo engagement starts with a conversation about the market, the buyer, and where the leverage is.

Start a Conversation
More from the Journal
Whitepaper
The Trust Economy
13 min readRead →
Market Intelligence
What HCM Platforms Aren't Telling Their Clients
6 min readRead →
Back to Journal
Market Intelligence

What HCM Platforms Aren't Telling Their Clients

HCM platforms influence more HR technology decisions than most buyers realize, and much of that influence is hard to see.
George RiveraApril 20266 min read

Most HR leaders think about their HCM platform as a system of record.

That is true as far as it goes.

A major HCM or payroll platform is also a market map, a partner ecosystem, a product roadmap, a referral engine, a competitive filter, and sometimes an invisible hand in the vendor selection process.

Platforms are strategic companies with their own incentives, as any company would be.

The problem is that most buyers do not see those incentives clearly enough.

Your platform has a point of view

Every major HCM platform has a view on the categories around it: benefits, payroll, learning, performance, compensation, engagement, recruiting, workforce planning, and employee experience.

In some categories, the platform wants to own the workflow. In others, it wants partners. In others, it will support integration but prefer the native path.

That matters because the platform's point of view shapes what clients see.

A vendor can be technically integrated and still commercially irrelevant. Another vendor can be a preferred partner and get pulled into deals before the buyer has completed the evaluation. A third may compete too directly with the roadmap and find itself deprioritized.

The buyer often never sees that map.

The three tiers of HCM partnership

Most third-party vendors inside a platform ecosystem fall into one of three practical categories.

  • Strategic partners. These vendors have deep integration, account-level trust, marketplace visibility, and some level of co-selling or mutual field awareness. The platform has a reason to recommend them.
  • Listed partners. These vendors are present in the marketplace and may have functional integration, but they are not actively pulled into deals. They win when the client already knows to ask for them.
  • Competitive partners. These vendors may integrate with the platform, but the platform also has a product, roadmap, or commercial interest that overlaps with them. The relationship exists, but the field motion may not favor them.
Your HCM platform has a strategic view on every vendor in your stack. The question is whether you know what that view is.

What this means for HR leaders

For HR and People leaders, the lesson is to keep working with your platform and understand its incentives.

When you ask your HCM or payroll provider for recommendations, you receive a view filtered through the platform's strategy, partnerships, product roadmap, and commercial priorities.

That view is useful and incomplete.

Before making a major HR technology decision, buyers should run at least one evaluation path outside the platform-recommended list. Ask peers, practitioner communities, and advisors who do not make money from the platform. Ask what the platform is building next and where its roadmap may overlap with the vendor you are considering.

The best HR leaders treat the platform's perspective as one input and keep the judgment for themselves.

What this means for vendors

For HR tech founders, the implication is obvious but often ignored.

Your relationship with the major HCM and payroll platforms can shape your entire addressable market.

Being a strategic partner, a listed partner, or a competitive partner changes how deals move, how buyers perceive risk, and how account teams talk about you. It can determine whether you get pulled into the right conversations or spend years fighting from the outside.

And the criteria for moving up that ladder go well beyond product quality.

The platform has to trust your company. Your integration has to work, your field story has to be easy to understand, and your customer overlap has to make sense. Your partnership team has to create value for the platform before it asks for referrals.

That is slow work, and companies building in this market cannot skip it.

§George Rivera · Founder, Tharseo Group

Working out your HCM platform strategy?

If you are a founder building inside a platform ecosystem, or an HR leader who wants a clearer view of one, let's talk.

Start a Conversation
More from the Journal
Whitepaper
The Trust Economy
13 min readRead →
Distribution
Why HR Tech Distribution Is Broken
8 min readRead →
Back to Journal
Operator Perspective

The Operator's Case for Employee Benefits as a Distribution Channel

For decades, benefits have been treated as a cost center. The next generation of companies will treat them as a trusted distribution channel.
George RiveraApril 20267 min read

Most CFOs have a simple mental model for employee benefits.

Benefits are a cost: large, growing, and one that has to be benchmarked, contained, justified, and renewed every year under pressure.

That view is understandable. It is also becoming incomplete.

For certain categories, including financial wellness, family safety, caregiving, health navigation, preventative care, education, and identity protection, the employer channel is becoming a distribution channel.

What changed

Three shifts have changed the economics.

First, employers can reach employees more directly. A generation ago, benefits communication meant open enrollment packets, email reminders, posters, and maybe a webinar. Today, employers have mobile apps, intranets, Slack, Teams, payroll surfaces, benefits portals, ERGs, manager channels, and employee communications infrastructure.

That matters because distribution is only valuable if the message can reach the person.

Second, employees expect consumer-grade experiences. The comparison set for a benefits product is now every app employees use in the rest of their lives. The products that win will feel simple, useful, and worth returning to.

Third, companies need new ways to create employee value. Wages, healthcare costs, and retention are all under pressure. Employers are looking for benefits that improve employees' lives in ways that show up in engagement, productivity, loyalty, or financial stability.

In the right category, benefits is a trusted path to the employee.

What distribution means here

Employers reselling products to employees is usually a bad idea. Distribution here means something more specific.

A well-designed benefit gives a company a recurring, trusted, high-attention way to reach employees in categories where consumer companies spend heavily to acquire those same users.

Family digital safety, caregiving, financial wellness, preventative health, college planning, debt support.

Delivered through the employer, these products arrive with a level of trust that most direct-to-consumer brands have to pay heavily to earn.

The employee assumes the employer has vetted the product. The product gets introduced at a moment when the employee is already thinking about support. The employer has a reason to communicate it more than once. That changes the economics.

Why this matters for operators

If you are building a consumer or prosumer product in a category connected to employee wellbeing, the employer channel deserves a look as your primary motion.

For the right product, B2B2C through the employer may be the best path.

It can lower customer acquisition cost, improve retention, create recurring engagement, and put the product in front of the right population with built-in trust. There is friction. Benefits sales cycles are slow, broker dynamics are complicated, HR buyers are careful, and procurement can be painful.

But once the channel works, the economics can be structurally attractive.

That is why companies like One Haven are leaning into employer distribution as a primary strategy. The thesis is that employer distribution, in the right category, may now beat consumer distribution.

What this means for HR leaders

For HR leaders, this shift creates an opportunity.

Benefits can become more than a renewal exercise. They can become a curated portfolio of products and services that support employees in the parts of life that most affect their ability to show up at work.

It takes better choices, and the budget can stay the same.

Which categories matter most to your workforce? Which products will employees use? Which vendors create measurable value? Which benefits support retention, engagement, financial stability, family wellbeing, or manager effectiveness?

The HR leaders who answer those questions well will have an advantage, because they understand benefits as part of the employee experience.

§George Rivera · Founder, Tharseo Group

Building for the employer channel?

Tharseo works with companies that reach employees through the employer channel. If you are building one, we want to hear from you.

Start a Conversation
More from the Journal
Whitepaper
The Trust Economy
13 min readRead →
Distribution
Why HR Tech Distribution Is Broken
8 min readRead →
About

Built from two decades inside workforce technology.

Tharseo Group is an operator-led firm for HR technology, payroll, and benefits companies.

George Rivera, Founder and Principal of Tharseo Group
Leadership

George Rivera

Founder & Principal, Tharseo Group

George Rivera has spent two decades building businesses and scaling revenue organizations in HR technology, payroll, and benefits.

He has also advised Fortune 500 CHROs, so he knows from the buyer's side of the table how large enterprises evaluate, buy, and adopt workforce technology.

He founded Tharseo Group after watching strong companies stall for lack of commercial architecture or market relationships. Tharseo combines strategic advisory, go-to-market execution, and capital to fix that.

Related ventures

Two ventures keep Tharseo close to the senior HR leaders who buy workforce technology.

People Performance Institute
IO psychology for mid-sized businesses.
Visit PPI
thesis.
An institute for the future of work.
Visit thesis.
Contact

Start the conversation.

For companies building, backing, or scaling in HR tech, payroll, and benefits.

Tell us what you are working on.

Share the company, the stage, and the problem.

Thank you. We read every message and reply when there is a fit.
Prefer to Talk?

Book 30 minutes on the calendar.

Book a Call
Direct Email
hello@tharseo.io
Based In

Washington, DC · Available globally.

Response Time

Typical response within 2 business days.